Jonathan Ayala began looking for a home in Hoboken, New Jersey, without considering new construction. The real estate agent and owner of a photography and marketing business instead focused on the costs involved in buying and owning a property. After viewing 10 homes in person, however, he found that none made enough financial sense to buy.Ayala looked beyond the asking prices of the properties. He also considered their condition, the repairs and upgrades they might need, and the financing involved. “I wanted to see the condition of each property, what repairs and upgrades were recommended, and the financing and overall cost of owning each property,” he says, as quoted by Realtor.com.Some of the older homes needed major work. Several required new roofs, while one had water damage. Ayala realised that negotiating a lower purchase price would not necessarily make those properties a better deal if he still had to spend heavily on repairs before moving in.“It was both exciting and frustrating,” Ayala says of the house hunt, which lasted roughly a month. As he compared each property, the search increasingly became a calculation of the asking price against the cost of repairs, renovations and future maintenance.“These homes were appealing at first, but all the repair, renovation and maintenance and other costs can add up fast,” he says. That calculation changed when a newly built home appeared within the price range he had been considering.
A new construction changes calculation
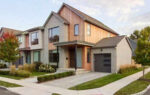
Ayala found a three-bedroom, 2.5-bathroom townhouse in Easton, Pennsylvania. The new-construction property was listed for $575,000. Rather than simply accepting the listed price, he began discussions with the builder about the terms of a possible purchase.Those discussions introduced another part of the calculation: builder incentives. Ayala says the incentives were not offered immediately, but he eventually secured a package worth $30,000.To receive the full incentive package, Ayala had to use the builder’s preferred lender and title company. The $30,000 was split between different parts of the purchase rather than being given as a single reduction in the sale price.“For me, the $30,000 was a more meaningful incentive because it lowered several real costs of the home purchase versus just a headline number.”The package included $15,000 towards closing costs, $10,000 towards a mortgage-rate buydown and $5,000 for interior finish upgrades. The mortgage-rate buydown was particularly important to Ayala because it reduced the rate from a possible 6.25% to 5.25%.
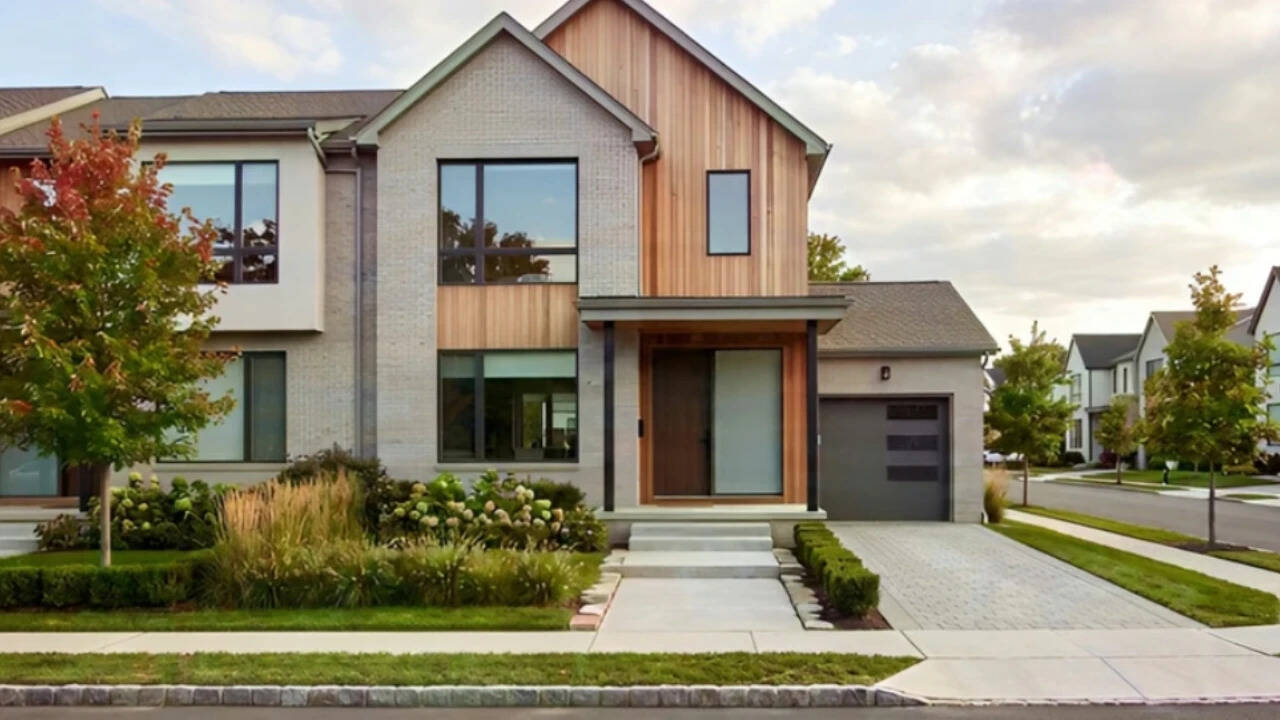
Ayala found a three-bedroom, 2.5-bathroom townhouse in Easton, Pennsylvania
Mortgage rate falls from 6.25% to 5.25%
The lower mortgage rate changed the monthly cost of the purchase. Ayala says the buydown reduced his monthly principal and interest payments by about $350 compared with the rate he would otherwise have received.“This lowered my monthly principal and interest payments by about $350 compared to the rate I would have received,” he says.The purchase price also changed during negotiations. Ayala was able to bring the price of the townhouse down from $575,000 to $545,000.He put down $109,000, which was 20% of the purchase price. Following the down payment, his monthly mortgage payment was $2,408.With both the purchase price and financing terms on the table, Ayala went back to the comparison that had shaped his original search. He looked again at the older homes he had already visited and considered what each would have cost after repairs and other work.“I did a much closer comparison with the pre-existing homes that I had already looked at and was considering—that’s when the offer became that much more interesting.”
He wanted to see the finished property
The financial terms were important, but Ayala also wanted to make sure the finished townhouse matched what he was actually considering buying. He returned to the builder and toured a townhouse that had already been completed.That allowed him to see the finished property instead of relying only on a model home. “I was able to evaluate the actual finished property and that was important to me,” he says. “I didn’t want to make a decision based on the appeal of a model home. I wanted to make a decision based on what I would actually purchase. Walking through the finished home gave me a real feeling of it; it was not a leap of faith,” he says.Once the price and other terms were agreed, Ayala says the transaction and closing went smoothly. The decision also left him satisfied with the overall deal. “There’s no question I got a much better package overall by buying new construction.”